MEIS Taxation Controversy: Arun Goyal Raises Concerns Over the Tax Burden on Export Incentives
An editorial perspective on export competitiveness, tax uncertainty and the need for policy clarity
India wants to be a global manufacturing and export power, and that takes more than factories and investment. It takes a policy environment businesses can predict. Exporters need to know where they stand on incentives, tax and regulatory duties before they can compete with confidence abroad. The MEIS taxation controversy, over how benefits earned under the Merchandise Exports from India Scheme (MEIS) should be taxed, puts that need squarely in focus.
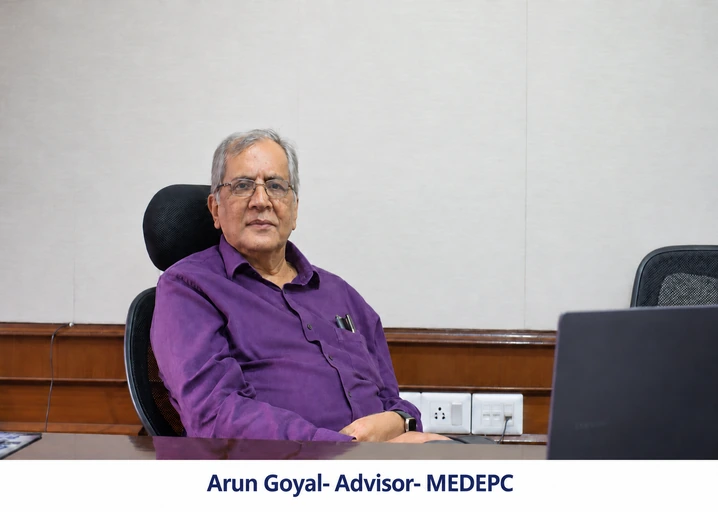
Arun Goyal, Director of the Academy of Business Studies, Delhi, and Advisor to MEDEPC, says the MEIS taxation controversy deserves careful thought in the wider context of export competitiveness. Drawing on his background in trade policy, customs and regulatory affairs, he raises a basic concern: support meant to offset the disadvantages exporters face should be judged against its original purpose as well as the tax law that applies.
What MEIS Was Meant to Do
MEIS rewarded eligible Indian exporters with duty credit scrips, issued at set rates for notified products and export categories. The scrips were transferable and, subject to conditions, could be used to pay certain customs duties.
The scheme worked in a tough global setting. Indian exporters often carried extra costs from infrastructure gaps, logistics expenses and other operating disadvantages, while competing with firms in countries like China, Vietnam and Thailand that had built strong manufacturing and export ecosystems. Goyal’s view is that export incentives were meant to help Indian businesses absorb some of these disadvantages and compete better, and that they tied into wider goals such as jobs, manufacturing growth and foreign exchange earnings.
The Policy Purpose
Offset cost disadvantages faced by exporters, and support employment, manufacturing growth and foreign exchange earnings.
The Tax Question
Whether MEIS benefits count as taxable income, which turns on the statutory provisions, judicial interpretation, assessment status and the facts of each case.
So the central question is how that original purpose should weigh when the tax treatment of MEIS benefits is decided.
When Export Support Becomes a Tax Dispute
At the heart of the MEIS taxation controversy is whether MEIS benefits count as taxable income under the Income-tax Act. Amendments brought in during 2015 dealt with how specified government assistance, including subsidies and incentives, is treated. Later tax disputes and tribunal decisions have pushed the question of how those provisions apply to MEIS into sharper focus.
For exporters, the consequences can go beyond a single tax bill. Businesses that took benefits under an established government scheme may now have to look again at their tax positions, review earlier assessments and weigh what relevant judicial decisions could mean for them.
Goyal’s worry is the uncertainty. Exporters plan around the rules in force, and when the tax treatment of an incentive is disputed, financial planning, working capital and trust in the policy framework can all suffer. Still, the legal position cannot be generalised across every exporter. Taxability, assessment proceedings and possible liabilities depend on the statutory provisions, judicial interpretation, assessment status and the facts of each case.
“You Are Giving With One Hand and Taking Away With the Other”
Goyal’s sharpest line on the issue is the observation below.
It sums up the tension. An incentive meant to help businesses get past specific cost disadvantages can end up adding a financial burden if its tax treatment is unclear. For firms on thin margins, a surprise liability can bite, cutting into money that would have gone to expansion, technology upgrades or hiring, and disputes over earlier years bring compliance costs of their own.
The issue, then, is bigger than how to classify one receipt. It raises questions about how incentives are communicated, implemented and assessed under tax law. Goyal’s point is that policy aims need to line up with clear legal provisions, so businesses can see the consequences of joining a scheme.
Why Policy Consistency Matters
Export incentives cannot be viewed apart from India’s wider trade strategy. The country wants more exports, stronger domestic manufacturing and more jobs, while keeping to its international trade commitments. The World Trade Organization’s rules on export subsidies have shaped how India’s export support has evolved. MEIS belonged to an earlier framework, and other mechanisms have since been introduced to support manufacturing and industrial growth.
For Goyal, the lesson is that support schemes should be designed with both international obligations and domestic tax consequences in mind. Businesses should know what a scheme offers and also the conditions and tax implications attached. That matters most for schemes that shape long-term investment, production and export decisions, where clear rules from the start reduce uncertainty and help firms plan.
Resolving the MEIS Taxation Controversy
Settling the MEIS taxation controversy means weighing the applicable law along with the concerns exporters have raised. The editorial sets out three routes, none of them a complete answer on its own.
Individual taxpayers must keep assessing their own circumstances under the law. The aim, as the editorial frames it, is a transparent and consistent position that lets businesses understand their obligations, cuts avoidable uncertainty and respects the rule of law.
Lessons for Future Incentive Schemes
The MEIS taxation controversy points to a lesson for future schemes: explain the tax treatment alongside the benefit. If businesses cannot confidently work out the financial consequences of government support, budgeting, compliance and investment planning get harder, and the certainty that good industrial and export policy is meant to give is weakened.
A predictable framework does not mean every incentive gets the same tax treatment, since schemes differ in aims and structure and their legal treatment must follow. It means the rules should be clear, consistent and easy for businesses to find. For a country trying to play a bigger part in global supply chains, that clarity is part of building investor confidence and supporting sustainable growth.
Conclusion: Competitiveness Requires Clarity
The MEIS taxation controversy shows how export policy, taxation and business confidence are tied together. Incentives exist to support competitiveness, but doubt about their tax treatment can leave recipients with financial and compliance headaches. Goyal’s perspective asks that the original goals of government support be examined while respecting the applicable law and court interpretation, and his worry is that policy uncertainty should not become an avoidable hurdle for exporters already working in a demanding international market.
As India pursues its manufacturing and export ambitions, clearer design and tax treatment of incentives can help businesses plan with confidence. A transparent, predictable and legally sustainable framework would bring policy intent and implementation closer, and let Indian exporters focus on winning in global markets.
At a Glance
Quick Answers
What is the MEIS taxation controversy?
The dispute over whether benefits received under MEIS should be treated as taxable income under the Income-tax Act, following the 2015 amendments and later disputes and tribunal decisions.
What was MEIS designed to do?
To support eligible exporters with transferable duty credit scrips, helping them manage cost disadvantages when competing with countries such as China, Vietnam and Thailand.
What is Arun Goyal’s main concern?
That support meant to offset exporters’ disadvantages should be examined against its original purpose and the applicable tax law, and that tax uncertainty can hurt planning and confidence.
Is the position the same for every exporter?
No. It depends on the statutory provisions, judicial interpretation, assessment status and the facts of each case.